Bank Loan Documentation
Preparing and perfecting home loan documents: the facility agreement, the charge or deed of assignment, stamping, and coordination of the loan release.

Bank loan documentation is the set of security documents prepared by the bank panel lawyer once you accept the letter of offer. Legal fees for loan documentation follow the loan amount, not the property price, on the same scale under the Solicitors Remuneration Order 2023. For a loan of RM450,000 the fee is approximately RM5,625 before service tax, and the loan agreement stamp duty is 0.5%, which is RM2,250.
The bank loan documentation process step by step
Where a property purchase is bank financed there are two separate sets of documents. The first is the sale and purchase agreement between you and the seller. The second is the loan documentation between you and the bank.
Each carries its own legal fee, the first calculated on the property price and the second on the loan amount. Many buyers are surprised to see two fee lines in a quotation. That is why.
Charge or deed of assignment in bank loan documentation
The bank requires security over the property. The form it takes depends on whether individual title has issued.
Where an individual or strata title exists, security is given by a charge registered at the land office. Where the property is still under the developer master title, security is given by a deed of assignment, because there is no separate title capable of being charged yet.
Letter of offer terms to check before bank loan documentation
The letter of offer binds you once accepted. Among the terms that most often matter later: a lock-in period imposing a charge if you redeem early, insurance the bank requires you to take, and the conditions precedent that must be satisfied before funds are released.
Why there are two sets of fees in one purchase
A bank-financed purchase involves two separate contracts. The first is between you and the seller, the sale and purchase agreement. The second is between you and the bank, the facility agreement and the security documents. Each has its own fee scale under the Solicitors Remuneration Order.
Bank loan documentation fees are calculated on the loan amount. Two buyers paying the same price for a property can therefore pay different legal fees if their loan margins differ. A buyer taking a 90% loan pays more than one taking 70%.
Stamp duty also arises twice in different contexts: once on the transfer, and once on the loan security document. Both must be settled before registration can proceed.
What the loan solicitor actually prepares
The fee is for a defined set of documents, and it is worth knowing what they are so you can tell what you are paying for.
| Document | What it does |
|---|---|
| Facility agreement | Sets out the loan amount, rate, tenure and the terms you are bound by |
| Charge, Form 16A | Registers the bank interest against an individual or strata title |
| Deed of assignment | Used instead of a charge where no individual title has issued yet |
| Power of attorney | Allows the bank to deal with the property if the loan goes into default |
| Letter of set-off | Lets the bank apply your deposits against the outstanding loan |
Which of these applies depends on whether an individual title has issued. A property on a master title uses a deed of assignment and a power of attorney. Once the individual title issues, a charge replaces that arrangement, and that later step is a separate matter with its own fee.
Documents you need to prepare
- Identity card, front and back
- The signed letter of offer from the bank
- Three recent payslips and the latest EA form
- Six months of bank statements
- EPF statement, where Account 2 is being used
- The sale and purchase agreement, once signed
- Marriage certificate, where the bank requires spousal consent
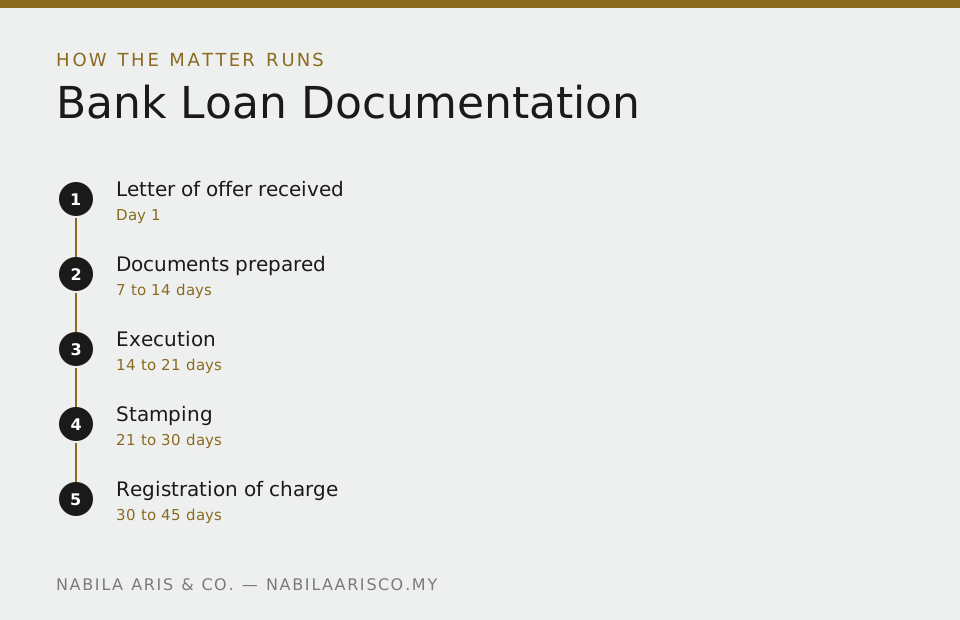
Timeline for loan documentation
| Stage | Usual duration |
|---|---|
| Accepting the letter of offer | Within the validity period stated, often 14 to 30 days |
| Bank instructs its panel solicitor | 1 to 2 weeks |
| Drafting and signing the security documents | 2 to 3 weeks |
| Stamping and presentation | 2 to 4 weeks |
| First disbursement to the seller or developer | After the documents are perfected |
The loan side and the purchase side run in parallel, not one after the other. A delay on either side holds up completion, which is why both solicitors need the same set of dates from the start.
Terms in the letter of offer worth reading twice
- Lock-in period and the early settlement penalty. Settling early within the lock-in usually triggers a penalty calculated on the original loan amount, not the balance. If you expect to sell or refinance within a few years, this is the term that costs the most.
- Whether the legal fee is absorbed. Some packages absorb the loan documentation fee and stamp duty. Where they do, there is usually a clawback if you settle early.
- Insurance requirements. Mortgage reducing term assurance and fire insurance are often conditions of the loan. Check whether you must take the bank panel product or may buy your own.
- The release schedule for a property under construction. Progressive release means you service interest on what has been drawn down before you hold the keys. Know what that monthly figure looks like through the construction period.
Terms in the letter of offer that change your cost
Read the sections on processing fees, insurance and early settlement penalties. Some banks offer a lower rate but impose a longer lock-in period, and that penalty becomes a real cost if you sell or refinance within it.
Check too whether the bank offers a package that absorbs legal fees and stamp duty. If it does, your loan amount rises, and the loan documentation fee rises with it because it is calculated on the loan amount.
One more thing that is often missed: the expiry date on the letter of offer. If the matter drags past that date the application has to be revived, and the valuation may have to be redone.
What your lawyer handles
- Reviewing the letter of offer and explaining the terms that affect you
- Preparing the facility agreement in the bank's format
- Preparing the security document, being a charge where individual title has issued, or a deed of assignment where the property is still under a master title
- Attending to stamping of the loan documents with the Inland Revenue Board
- Presenting the charge for registration at the land office
- Coordinating with the bank for release of the loan to the seller or developer
- Ensuring any insurance required by the bank is in place before release
Timeline
Documents you need to prepare
- Letter of offer from the bank
- Copy of the identity card of the borrower and any guarantor
- Copy of the signed sale and purchase agreement
- Copy of the title, or the original agreement if the property is under a master title
- Details of MRTA or MRTT insurance if required by the bank
Costs people often overlook
- Legal fees calculated on the loan amount, not the property price
- Loan agreement stamp duty at 0.5% of the loan amount
- Land office fee for registration of the charge
- Service tax of 8% on legal fees
- Search and document delivery costs
When to stop and get advice first
- The letter of offer contains terms that differ from what the officer described verbally
- The bank requires a guarantor, but nobody has explained the implications of the guarantee to that person
- A lock-in period that imposes an early redemption charge if you sell or refinance
- The approved loan is lower than applied for, leaving a shortfall you have to fund in cash
Frequently asked questions about bank loan documentation
Why are there two sets of legal fees?
The sale and purchase agreement and the loan documentation are separate matters with different documents. The scale applies separately to the property price and to the loan amount.
What is the difference between a charge and a deed of assignment?
You register a charge where the individual title has issued. Where the property still sits under the developer master title, with no separate title to charge, you use a deed of assignment instead.
Can I choose my own lawyer for the loan documentation?
The bank appoints from its panel. If your preferred firm sits on that panel, you can ask the bank to appoint it.
How does Islamic financing differ in terms of documents?
The contract structure differs. Islamic financing typically uses a commodity sale or lease based contract, while a conventional loan uses a loan agreement. The underlying security documents are broadly similar.
How long before the loan is released?
Normally one to two months after you sign the documents, subject to stamping, registration, and the bank's conditions for release.
Ready to start your property matter?
An initial consultation with no obligation. Tell us about your matter and we will explain what is involved and what it is likely to cost.
No 1, Jalan Setia Dagang AL U13/AL, Setia Alam, 40170 Shah Alam, Selangor
014-4004293 · Monday to Friday, 9:00am to 5:00pm